Let's KINNECT!
"*" indicates required fields
"*" indicates required fields
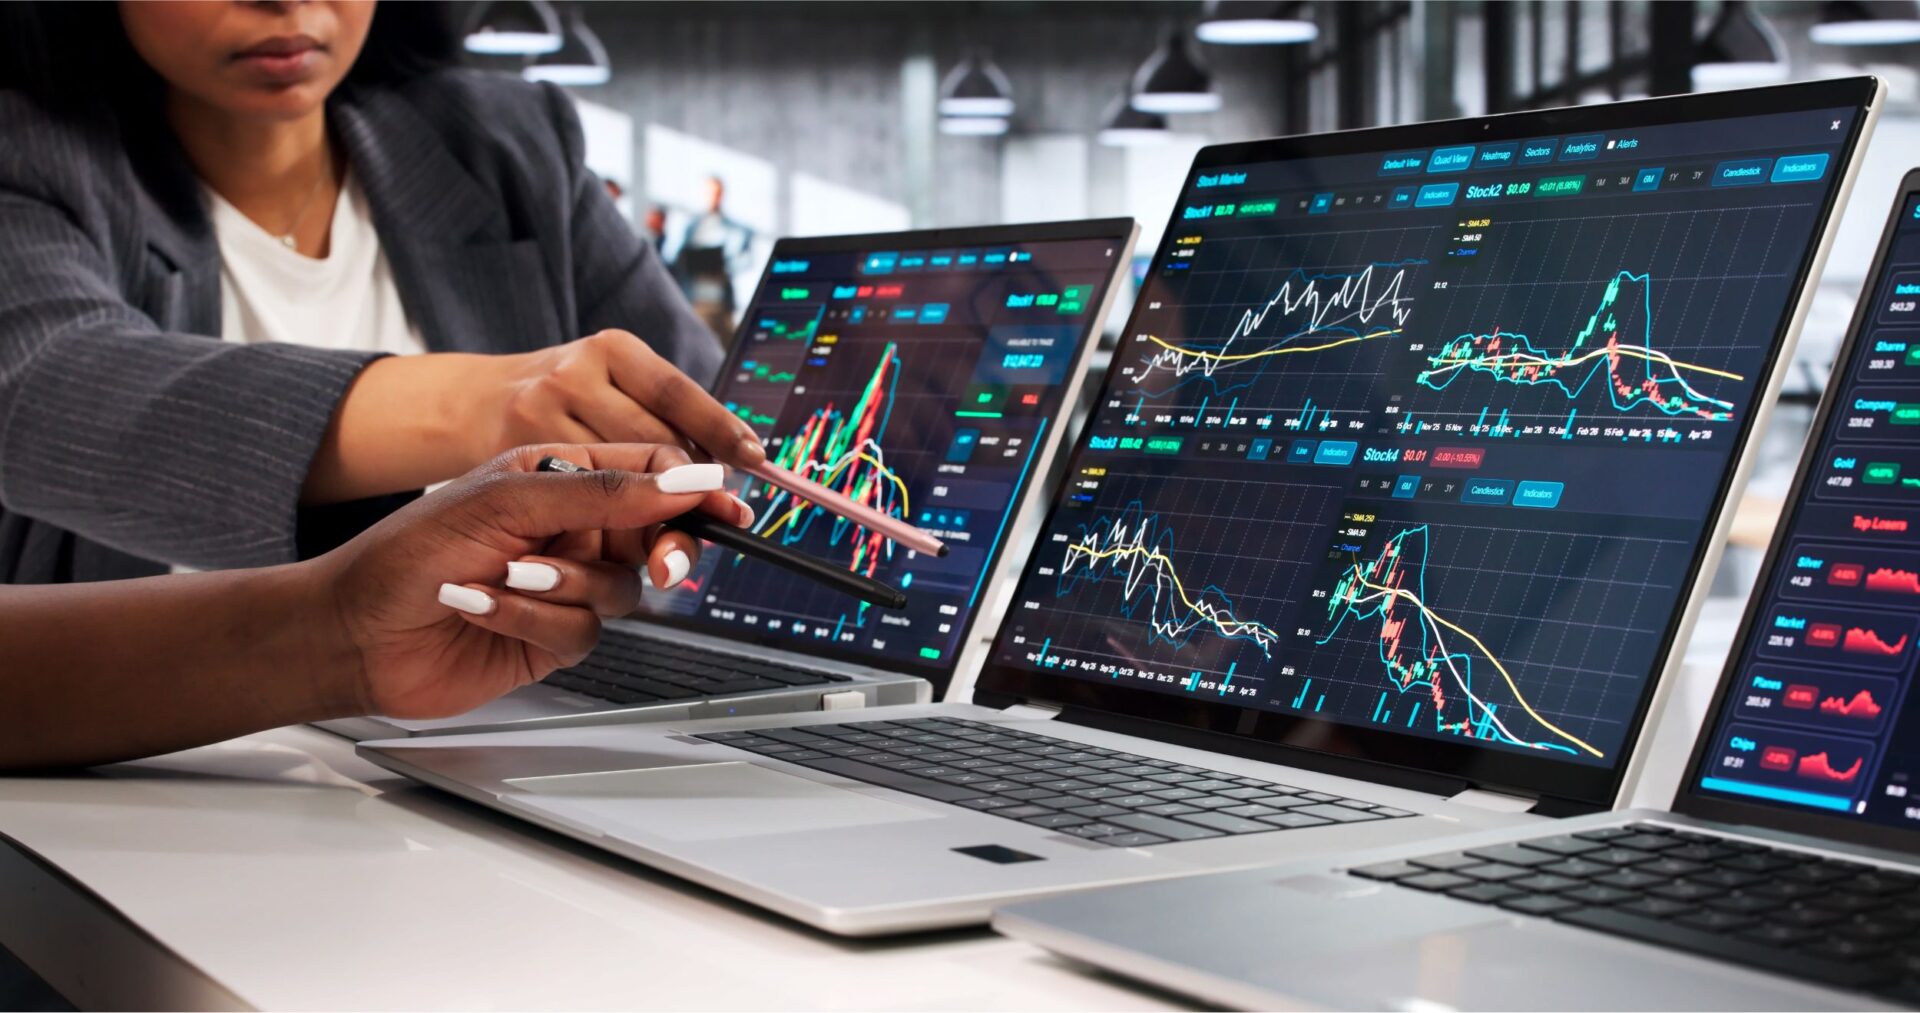
Money has different jobs at different stages of life. Early on, the priority may be turning income into investments that can fund retirement, education, a business purchase, or future independence. Later, the central concern often shifts toward keeping those resources available through market declines, taxes, inflation, health expenses, and transfers to family members.
The distinction is not simply “growth versus safety.” Accumulation and preservation are connected disciplines with different objectives, risks, and measures of progress. KINNECT Financial helps individuals, families, and business owners coordinate both so that decisions made to build capital do not conflict with plans for using or transferring it.
Wealth accumulation is the process of consistently directing earnings and existing assets toward long-term growth. Common methods include contributing to retirement accounts, investing in taxable portfolios, reinvesting business profits, acquiring real estate, and maintaining enough liquidity to avoid selling long-term holdings for routine expenses.
Time is a major resource during this phase. A longer horizon may allow an investor to accept more short-term price movement in pursuit of higher potential returns, although every investment carries risk. Contributions, savings rates, taxes, fees, and investment performance all influence the result. Automated contributions can support consistency, while periodic increases may keep the savings plan aligned with rising income. Progress is usually measured against a defined goal rather than a market index alone.
Our financial advisor can examine how savings, investments, taxes, insurance, and future income work across multiple goals. If your assets have grown without a coordinated plan for their next purpose, schedule a financial review with us. An early assessment can show whether current decisions still support the responsibilities ahead.
The goal of wealth preservation is not to eliminate every loss or stop pursuing growth. It is to reduce the chance that one event, concentrated position, tax liability, lawsuit, business setback, or poorly timed withdrawal will materially disrupt the owner’s plans. The relevant question changes from “How much can this become?” to “How much must remain available, for whom, and when?”
Preservation may involve greater diversification, dependable liquidity, insurance, thoughtful account ownership, tax planning, estate documents, and a withdrawal policy. These elements serve different purposes. Holding excessive cash, for example, may reduce short-term volatility but leave purchasing power exposed to inflation. A plan must balance competing risks rather than respond to only the most visible one.
There is rarely a single date when growth ends and preservation begins. A business owner approaching a sale may still need long-term portfolio growth, while a retired household may preserve near-term spending reserves and invest other assets for decades. The correct balance depends on cash-flow needs, time horizon, health, family commitments, taxes, and tolerance for loss.
Regular reviews help identify when allocations, cash reserves, insurance, or withdrawal plans should change. This allows the approach to evolve without forcing an abrupt shift after a major event occurs.
Asset allocation determines how a portfolio is divided among categories such as stocks, bonds, and cash. Diversification spreads holdings across and within those categories. Investor.gov explains that diversification can reduce risk, while rebalancing restores a portfolio to its intended allocation after market movements alter the mix. Neither method guarantees against losses.
Effective wealth management also considers risks outside an investment account. An emergency reserve can reduce forced sales. Appropriate insurance can shift certain financial exposures. Tax-aware withdrawals may extend the useful life of assets, while updated beneficiary designations and estate documents help direct property as intended.
An accumulation plan may track savings, contribution increases, expected returns, and progress toward a future capital target. A preservation plan may emphasize sustainable withdrawals, liquidity, tax exposure, insurance adequacy, concentration, and the amount intended for heirs or charitable organizations. Both sets of measurements should reflect inflation and changing personal circumstances.
Using the wrong measurement can prompt poor decisions. Someone focused only on returns may accept more risk than a near-term obligation permits. Someone focused only on avoiding losses may fail to generate enough growth to offset inflation and decades of withdrawals. Periodic reviews keep the measurement tied to the purpose of the money.
What should the next dollar accomplish: growth, income, liquidity, or a future gift? A clear answer helps determine which risks are reasonable and which ones may interfere with the plan. For clients in Florida and throughout the United States, KINNECT Financial brings investment, tax, insurance, retirement, and legacy considerations into the same conversation. Start a planning conversation with our team to give accumulated wealth a defined purpose across the years ahead.
This material is for informational and educational purposes only and is not intended as individualized investment, legal, or tax advice. Financial strategies, including those related to healthcare planning and long‑term care, are based on general assumptions and may not be suitable for every individual.
Securities and investment advisory services off ered through qualified registered representatives of MML Investors Services, LLC. Member SIPC. https://www.sipc.org/ Kinnect Financial is not a subsidiary or affi liate of MML Investors Services, LLC, or its affi liated companies. 1000 Corporate Drive Suite 700 Fort Lauderdale, FL 33334 (954) 558-8333
CRN202909-12091868